Money management can feel confusing at first, especially when people start hearing terms like credit score, credit history, and credit cards. Many beginners avoid learning about credit because it sounds complicated, but understanding the basics can make a big difference in your financial future.
A good credit score can help when applying for loans, renting an apartment, buying a car, or even getting approved for certain services. Credit cards can also be useful tools when they are used responsibly.
The good news is that learning about credit does not have to be stressful. Small habits and smart choices can help you build healthy financial habits over time.
What Is a Credit Score?
A credit score is a rating that reflects how well you handle borrowed money and repayments. Lenders and financial companies often use this score to decide whether to approve loans or credit cards.
Your credit score is usually based on things like:
• Paying bills on time
• How much debt you owe
• How long you have used credit
• The number of credit accounts you have
• Recent credit applications
A higher credit score generally shows that you are more reliable with payments.
Why Credit Scores Matter
Many people do not think about their credit score until they need it. Your credit score can influence many important parts of your financial life.
A good credit score may help you:
• Qualify for loans more easily
• Receive lower interest rates
• Get approved for apartments or rentals
• Increase chances of credit card approval
• Build stronger financial opportunities
On the other hand, poor credit habits can make borrowing more expensive and difficult.
What Is a Credit Card?
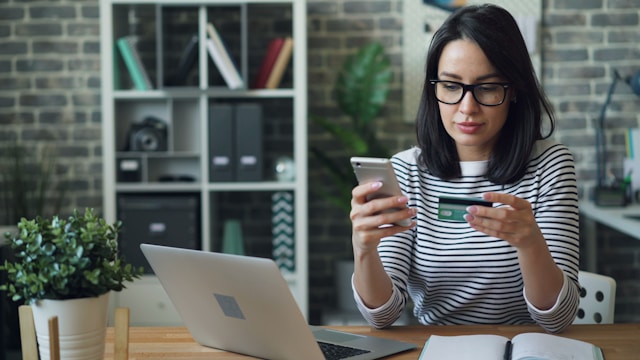
A credit card allows you to borrow money from a bank or financial company for purchases. You are expected to repay the money later, usually every month.
Unlike debit cards that use your own money directly from your bank account, credit cards use borrowed money with a spending limit.
People often use credit cards for:
• Online shopping
• Emergency expenses
• Travel bookings
• Everyday purchases
• Building credit history
When used carefully, credit cards can be convenient and helpful.
How Credit Cards Affect Your Credit Score
Your credit card habits can strongly impact your credit score. Responsible use may help improve your score over time, while poor habits can lower it.
Here are some important factors:
Paying on Time
The way you handle bill payments over time has a strong impact on how your credit score is calculated. Late or missed payments can lower your credit score faster than many people realize.
Even paying the minimum amount on time is usually better than missing a payment completely.
Keeping Balances Low
Using too much of your credit limit may negatively affect your score.
For example, if your credit limit is $1,000 and you spend $900 regularly, lenders may see this as risky.
Many experts recommend keeping credit usage lower when possible.
Applying for Too Many Cards
Opening several credit cards within a short time may temporarily lower your score.
It is often better to apply only for cards you actually need.
Benefits of Using Credit Cards Responsibly
Credit cards are not automatically bad. In fact, they can offer several benefits when managed properly.
Building Credit History
Using a credit card responsibly can help create a positive credit history over time.
This may help later when applying for loans or other financial products.
Convenience and Security
Credit cards are often safer for online purchases and may offer fraud protection if unauthorized transactions happen.
Rewards and Cashback
Some credit cards offer rewards programs, travel points, or cashback for purchases.
These benefits can be useful if spending stays under control.
Emergency Support
Unexpected expenses can happen at any time. A credit card may provide temporary financial support during emergencies.
However, it is still important to borrow carefully and avoid depending heavily on credit.
Common Credit Card Mistakes
Many financial problems begin with small habits that grow over time. Understanding common mistakes can help you avoid unnecessary debt.
Spending More Than You Can Repay
A major mistake people often make is treating credit card spending like free money instead of borrowed money that must be repaid.
Borrowed money still needs to be repaid, often with interest.
Missing Payments
Missing payments can result in extra charges and may negatively affect your credit score.
Setting reminders or automatic payments may help avoid this problem.
Only Paying the Minimum
Paying only the minimum payment each month can make debt last longer since interest keeps adding up over time.
Trying to pay more than the minimum can help reduce debt faster.
Ignoring Credit Reports
Checking your credit report occasionally can help you spot errors or suspicious activity.
Monitoring your credit regularly is part of healthy financial management.
Tips for Building Healthy Credit Habits
Building good credit takes time, but simple habits can make the process easier.
Create a Budget
A budget helps you understand how much money you earn and spend each month.
This can prevent overspending and help manage credit card payments more comfortably.
Pay Bills Consistently
Consistency matters more than perfection. Making payments on time regularly can help strengthen your credit history.
Use Credit Carefully
You do not have to rely on a credit card for every single purchase. Responsible and moderate use is often the safest approach.
Avoid Emotional Spending
Impulse purchases can quickly create unnecessary debt.
Taking time before making large purchases may help you make better financial decisions.
Build Slowly
Improving your credit score takes patience and responsible money habits over time. Small positive habits repeated consistently often lead to better results over time.
Understanding Interest Rates
Credit cards usually charge interest when balances are not fully paid by the due date.
Interest is the additional amount charged when you borrow money and do not repay it immediately.
Higher interest rates can make debt grow faster, especially when balances remain unpaid for long periods.Beforegetting a credit card, it helpsto understand:•Interest rates
• Annual fees
• Payment duedates
• Reward terms
• Penalty fees
Reading the details carefully canprevent surpriseslater.
Secured vs Unsecured Credit Cards
Some beginners may hear about securedand unsecured credit cards.
Secured Credit Cards
Secured cards usually require a deposit. They are often designed for people building or rebuilding credit.
Unsecured Credit Cards
Unsecured cards do not require a deposit and are more common for people with stronger credit histories.
Choosing the right option depends on your financial situation and goals.
Final Thoughts
Credit scores and credit cards may seem complicated at first, but learning the basics can help you make smarter financial choices. Credit itself is not necessarily good or bad — what matters most is how it is managed.
Building healthy credit habits takes patience, consistency, and responsible spending. Paying on time, avoiding unnecessary debt, and understanding how credit works can help create a stronger financial future over time.
Starting small is completely okay. Even simple financial habits today can make a big difference later.
No comments yet.